

Managed Service Providers of Digital Credit: The #cs183FANFE Joke That Became Infrastructure
Peter Thiel’s CS183: Startup at Stanford in 2012 was supposed to be the last class you needed.
Blake Masters’ notes turned it into Zero to One. The lectures covered monopoly theory, secrets, team, and the pitch. They did not cover the part where your company is healthy on paper and still gets managed by its own vendors, its own credit file, or a 60-day payment term that quietly becomes a 90-day problem because nobody on the founding team had ever been taught how the score actually moves.
Larry Chiang has spent years filling that gap under the hashtag #cs183fanfe. FANFE is a real Stanford GSB Executive Education program, “Finance and Accounting for the Nonfinancial Executive” run for mid-to-senior managers who already have titles and budgets and still cannot read a cash-flow statement without help.
The official version costs roughly $64,500–$80,000 on campus. Chiang’s version is the open, street-smart prequel aimed at CS majors and young founders: the finance and accounting they never get in stramgt353, chemical engineering 297, CS 183, ENGR 145, or the design School.
#cs183fanfe is the class that treats credit reports, treasury management, on-time payment strings, and vendor leverage as operational systems that can be monitored, patched, and managed the same way you manage endpoints.
A Managed Service Provider of Digital Credit is the joke that writes itself in that frame and then turns out to be true.
What an ordinary MSP actually does
A traditional Managed Service Provider takes ongoing responsibility for a client’s IT stack—monitoring, patching, backups, helpdesk, security, cloud administration—for a recurring fee. The economic incentive is aligned with uptime rather than billable incidents. The client stops calling a break-fix technician only after something breaks. That model works. It is also incomplete. The same company that has 24/7 alerts on disk space and phishing attempts often has no equivalent system for the credit file that determines whether a supplier will extend terms, whether a bank will fund inventory, or whether a late payment from one large customer creates a cascade that the IT team cannot see.
The #cs183FANFE diagnosis
Chiang’s #cs183creditScore writing makes the practical point explicit. A CS major with an 800 FICO and mastery of the CS183 material sees the world as code. The reverse is also true: without the credit and cashflow layer, the code does not ship because the company cannot buy the server, hire the contractor, or survive the quarter when the large customer pays late. He has described the protocol of 24 consecutive on-time payments (two years, two cards) as the operational path from a thin or nonexistent file to a usable score. He has pointed at real bank branches (the #530Lytton example) and at the difference between what Fair Isaac claims the average score is and what the operational reality looks like for people who have never been taught the rules. That is not theory. It is the same reverse-engineering approach he applied as an undergrad and later packaged as street-smart material for Stanford engineers.
Photo credit, Nico 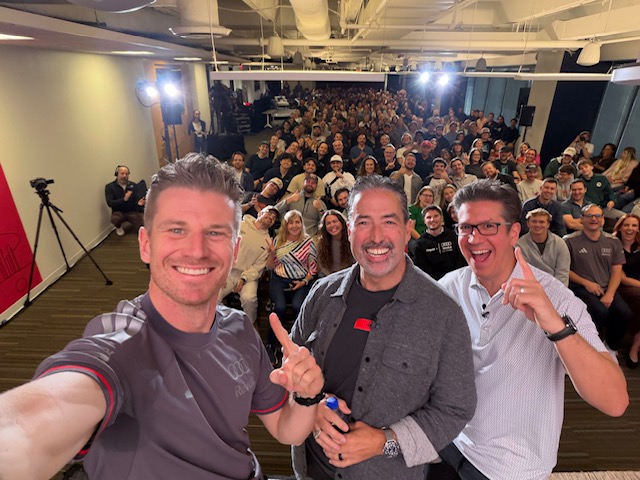
The joke is that Silicon Valley will spend large sums on AI agents that monitor your code and your firewall while the company’s actual credit utilization, trade lines, and vendor payment behavior sit in a PDF that gets looked at once a year, if at all.
A Managed Service Provider of Digital Credit simply treats the credit and cashflow layer as another system that can be monitored continuously, alerted on, and “patched” proactively.
What that looks like in practice (and already exists in pieces)
The pieces are real and already commercial:
• Credit bureaus sell continuous account monitoring and portfolio scoring services. Experian and Equifax offer tools that flag new derogatory information, track utilization, and surface changes across a customer or vendor base. These are not consumer apps; they are systems used by lenders and, increasingly, by companies that want early warning on counterparties.
• MSPs already run “credit control” operations for their own receivables: terms in the master service agreement, autopay as default, automated reminder ladders, and enforced late fees. One documented case (an MSP on Xero) cut late payments 60–70% after switching on automatic late fees and branded reminders. The same discipline applied outward—to a client’s vendors and to the client’s own trade lines—is a short conceptual step.
• Digital credit itself (app-based or embedded lending) has grown large enough that CGAP has published technical guidance on responsible practices precisely because overindebtedness, data misuse, and weak redress are now operational risks, not edge cases. A provider that monitors those risks for a small business is doing managed service work, not pure software.
Put the pieces together and the service is straightforward. The provider connects to the relevant credit and banking data feeds (with proper authorization). It monitors the client’s own business credit file, the payment behavior of key vendors, and the aging of receivables. It surfaces alerts the same way an RMM tool surfaces a failed backup: a sudden jump in utilization, a vendor that has historically been 15 days late now trending to 45, a trade line that is about to age into a reporting window. It can recommend or execute the operational “patch”, renegotiate terms, shift volume, accelerate collections, or open a small trade line that improves the file without increasing risk. The fee is recurring because the monitoring is continuous. The SLA is defined in the same language MSPs already use for response times and uptime.
Why the joke lands and then becomes true
The humor is pure Chiang: the people who can write the most sophisticated monitoring agents for servers still get surprised by the simplest cashflow arithmetic. CS183 taught the importance of secrets and distribution; it did not teach that a secret is worthless if the company cannot fund the inventory that distribution requires. FANFE exists at the GSB because even experienced executives need the basics. Chiang’s version for CS majors exists because the basics are still missing when the founder is 22 and the first large customer just pushed payment terms. An MSP that manages digital credit is the operationalized version of that missing class.
The “later-comes-true” part is already visible in adjacent markets. MSPs are expanding into AI governance and outcome-based services. Credit data providers are selling continuous monitoring rather than static reports. Small businesses are using digital credit products that create new risks that need ongoing oversight. The firm that simply combines the monitoring discipline of an MSP with the credit and treasury discipline of #cs183fanfe is not inventing a category; it is naming the category that already exists in fragments and selling the integrated version.
A CS major who has absorbed Thiel’s lectures, sat through Chiang’s practical credit material, and then hands the ongoing monitoring of the credit file and vendor terms to a specialist provider is doing exactly what the original MSP model did for servers: stop treating the system as something you only notice when it breaks. The rest is just operations
 |
||
|

 Duck9 is a credit score prep program that is like a Kaplan or Princeton Review test preparation service. We don't teach beating the SAT, but we do get you to a higher credit FICO score using secret methods that have gotten us on TV, Congress and newspaper articles. Say hi or check out some of our free resources before you pay for a thing. You can also text the CEO: